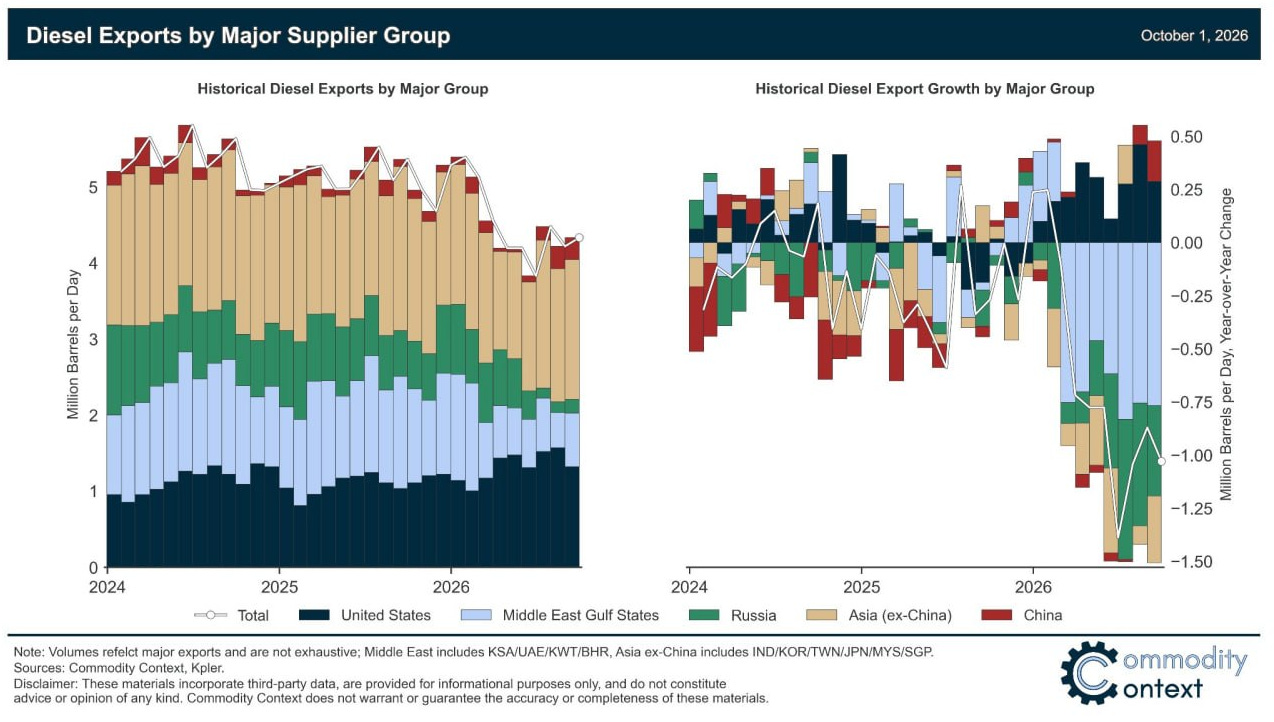

A remote-controlled boat costs less than a used car, and it can close a sea lane that took navies three centuries to open. I keep coming back to that asymmetry because it is the cleanest summary I have of the market we are now trading. Iran has stopped bothering with deniability. The East-West pipeline was hit by drones launched from Iraqi territory, Yanbu loadings were suspended, and Brent touched roughly $110 on the day. Tehran’s self-imposed 45-day deadline for Washington to lift the naval blockade has just expired, Trump has called its latest proposal unacceptable, and Iranian officials have floated an exclusion zone reaching into the Gulf of Oman, which moves the risk map from two straits towards an ocean. The Houthis, meanwhile, have opened a second front at Bab el-Mandeb. Every desk has a model of Europe that it never writes down, because writing it down would mean admitting it is a model. The European Union sits in the risk system the way the risk-free rate sits in Black-Scholes: you know it is not really constant, but you treat it as a parameter because treating it as a variable is too expensive to compute. My argument in this piece is that the parameter is turning into a variable, and that the market has not repriced for it. Rates and FX traders now have to think like oil traders, and oil traders have to think like geostrategists.
The thesis is simple enough to fit on a term sheet. The United States is pulling back into a hemispheric fortress. The Arctic matters more than any mineral deposit. The maritime order that underwrote cheap freight and cheap insurance is coming apart. And Europe, whichever way the great-power alignment settles, is the party that gets handed the bill. The only genuinely open question is where Russia lands in the new arrangement, and that question is where the unpriced risk sits. It helps to be precise about the vocabulary. A crisis is when secondary elements change and you can wait it out. A catastrophe is when the base elements break. A collapse is when the base itself is replaced. For most of the last fifteen years, European policy has been run on the assumption that it was living through a sequence of crises. I think it has crossed into the second category, and the distinction matters for anyone holding energy or shipping exposure with a European counterparty on the other side.
Start with Washington, because everything else follows from it. It is tempting to read Trump as noise, a personality layered on top of an otherwise stable foreign policy. I read him as a receiver. His whole career was buying half-dead assets and either restructuring them or putting them through bankruptcy, and the American establishment, having watched the globalisation project stall, appears to have handed him a mandate to restructure the United States itself. Remember that TTIP and TiSA were already dead in the water before Trump arrived. What we are seeing now looks less like improvisation and more like a divorce being prepared with lawyers. You get allies to sign up to defence targets of 3.5 and 5 per cent of GDP that most of them cannot meet. You ask them to help secure Hormuz, as Trump did in March, and note for the record that they declined. You convert Ukraine, within eighteen months, from the West’s war into Europe’s invoice, sell Europe weapons at a premium to pass on to Kiev, and then send the bill. Nobody walks out of a marriage of several generations overnight. They build the file first.